

Possible: Fast Cash & Credit
4.4

When a bill lands before payday, I can see why a short-term borrowing app might feel like a practical escape hatch. Possible: Fast Cash & Credit is built around that urgent moment, with a second aim: helping users establish credit through repayment. That combination is more interesting than a simple cash advance, but it also calls for a clear-eyed approach. I would treat it as a tool for a specific cash-flow gap, not as extra income or a routine way to cover monthly expenses.
Fast cash is the central promise—and the trade-off
Possible is a finance app from Possible Finance - A Public Benefit Corporation. Its focus is short-term borrowing and credit-building, rather than budgeting, investing, or managing every part of your financial life. The app is free to download, has an Everyone age rating, and is available for Android and iOS. It was released on January 25, 2018, and its current version is 2.4.2. Its 4.4 average rating comes from around 61,000 ratings, with about 29,000 written reviews, and it has been installed over a million times.
Those figures suggest a substantial audience, but they do not tell me whether a particular person will qualify, how much they may be offered, or whether borrowing will suit their budget. The useful question is not simply whether money can arrive quickly; it is whether the repayment schedule fits the next few weeks without forcing another loan. Speed only helps when the repayment is manageable.
What the credit-building angle changes
Many people compare emergency borrowing options only by how quickly funds might arrive. Possible adds a credit-building purpose: the original review describes payments being reported to credit bureaus, so keeping up with repayments may help build a payment history. That is a potential benefit, not a guaranteed improvement in a score. Credit outcomes depend on a person’s wider file and payment habits, and a missed payment can undermine the very goal that made the loan appealing.
I would therefore think of the credit feature as a possible side benefit of a loan I already have a sound reason to take—not as a reason to borrow when I do not need to. If your priority is improving credit, compare this route with options that do not require taking on short-term debt. A secured credit product or a credit-builder loan may fit some people better, depending on eligibility and terms. The important distinction is that Possible addresses an immediate cash need first; credit-building should not distract from the cost and timing of repayment.
How I would approach an application
The app’s onboarding is described as straightforward, with basic personal information, bank account details, and income information involved. I would prepare those details before starting and check that the account information is accurate. This is a practical step, not a promise of approval: an application still needs to be assessed, and the amount and timing available to one person may not match another person’s experience.
Before accepting an offer, I would read the repayment dates and total amount due together, rather than focusing on the cash arriving. Then I would compare those dates with confirmed income and essential bills. If the payment would leave too little for rent, food, utilities, or transport, the loan is not solving the whole problem; it is moving pressure to a later date. A quick written budget on paper or in a notes app can make that trade-off easier to see.
One useful habit is to decide in advance what the borrowed money is for and keep the amount tied to that expense. If a necessary repair costs less than the amount offered, taking more simply because it is available can make repayment harder without improving the outcome. I would also avoid treating a possible credit benefit as a reason to stretch beyond what I can repay comfortably.
A realistic use case—and when I would pause
Imagine a necessary car repair comes up a few days before payday, and without the car you cannot get to work. A short-term loan may be worth considering if the repair is confirmed, the amount is clear, and the next income can cover both the repayment and ordinary bills. In that situation, I would compare the loan with alternatives such as asking the repair shop about payment arrangements, checking whether a less expensive repair is safe, or seeing whether a trusted person can help without creating a bigger obligation.
The same app would be a poorer fit if the expense is recurring, uncertain, or nonessential. Borrowing for groceries every month, covering one loan with another, or relying on a future raise that has not arrived can turn a temporary bridge into a cycle. If several bills are already overdue, I would first contact the providers and ask about hardship options or a payment plan. That may take more effort than an app, but it avoids adding a new repayment before the existing budget is under control.
Compared with a bank personal loan, a short-term option may be more relevant when the need is small and time-sensitive, while a bank or credit-union loan can be more suitable for a larger planned expense or a longer repayment horizon. A credit card can be convenient for a purchase, but its interest and repayment rules need careful comparison too. Neither alternative is automatically cheaper or easier for everyone; the right comparison is the total cost, the due dates, and what happens if your income is delayed.
Reading the experience with care
The original review describes a clean, direct interface and support resources that include FAQs and chat. For a borrowing app, that kind of access matters most when a user needs to understand a repayment date, an application decision, or a problem with account information. I would save any important terms shown in the app and use the support channel for questions that affect my ability to repay, rather than relying on memory after tapping through the process.
Security deserves the same practical attention as convenience. The original account describes encrypted data and confidentiality, but I would still use a strong device passcode, keep the app updated, and avoid entering financial details on a shared or unsecured device. Those are sensible habits for any financial service; they do not remove the need to review what information an app requests or to protect access to the phone itself.
The app is free to download, but that should not be confused with borrowing being cost-free. The original review notes that rates may be higher than those for traditional loans, and borrowing terms matter more than the download price. Before agreeing, I would check the amount to repay, each due date, and any consequences of paying late. If any part of the offer is unclear, pausing to ask support is better than accepting based on the appeal of speed alone.
Who is most likely to benefit
I can see Possible being useful for someone facing a one-off, urgent expense who has income expected soon and a realistic way to meet the scheduled payments. The credit-building purpose may be relevant to a borrower who wants repayment activity to contribute to a credit history, provided they understand that no particular score increase is assured. For that person, the app’s focused approach may feel less complicated than a broader financial platform.
I would steer away from it if you need ongoing help balancing a budget, want a long-term loan, or cannot identify where repayment will come from. It is also not a substitute for financial counselling or for contacting creditors when existing bills are already unmanageable. A budgeting app can help track spending without adding debt; a nonprofit credit counsellor may be a more appropriate place to start when several obligations are competing for the same income.
There is no universal rule that a fast loan is always a bad idea or always a helpful one. The decision turns on the emergency, the exact repayment terms offered, and the rest of the month’s cash flow. I would use the app only after checking those pieces together, and I would keep the amount as small as the actual need allows. That makes the credit-building element a possible extra rather than the justification for borrowing.
Getting Started with Possible: Fast Cash & Credit
First things first, downloading the app is a breeze. Available on both Android and iOS, you can find it in your respective app store. Once installed, the user interface is refreshingly simple. No need to navigate through endless menus or flashy graphics; it’s all about functionality here.
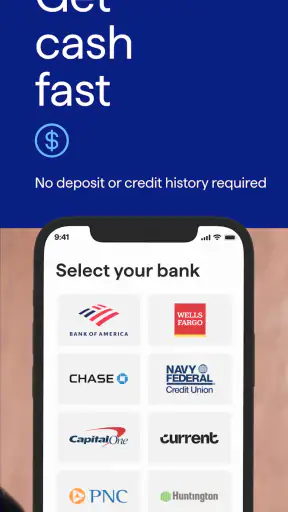
The registration process is straightforward. You’ll need your basic information, bank account details, and a steady income to get started. What stands out is the app's commitment to security. Your data is encrypted, and the app makes sure to keep everything confidential. This is a big plus in a world where data breaches are all too common.
How It Works
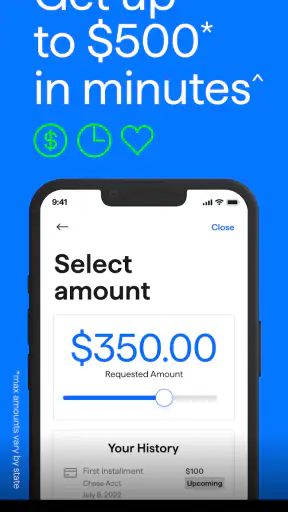
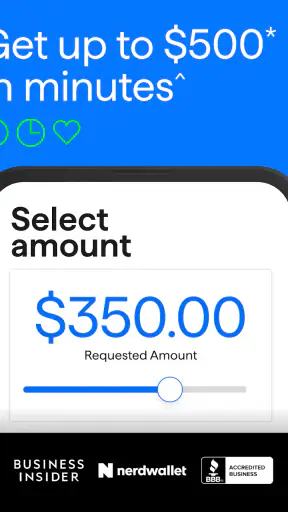
Unlike traditional lending methods that can take days (or even weeks), Possible: Fast Cash & Credit offers a streamlined approach. Once your application is approved, you can receive funds in as little as a few minutes. It's almost like having a financial safety net at your fingertips.
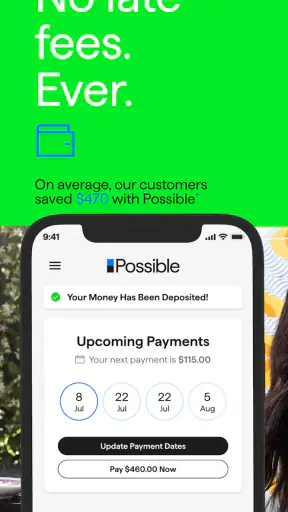
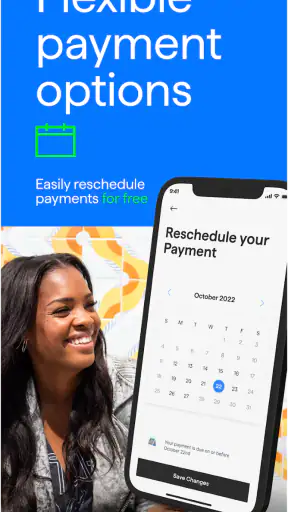
The app offers loans up to $500, which might seem modest, but it's perfect for those little emergencies when payday is just too far away. The repayment terms are flexible, allowing you to pay back in installments that won't break the bank. Plus, there are no hidden fees, which is a refreshing change from the usual lending practices.
Building Credit
One of the standout features of Possible is its commitment to helping users build their credit score. Every time you make a payment, it gets reported to the credit bureaus, which can help improve your score over time. This is perfect for anyone looking to boost their creditworthiness without getting caught up in high-interest debt cycles.
User Experience
The app's design is clean and intuitive. Navigating through it feels natural, with everything you need just a tap away. The support section is robust, offering FAQs and a chat option for direct communication with customer service reps. And let me tell you, their customer service is top-notch. I had a question about repayment terms, and they responded promptly with helpful information.
For those concerned about interest rates, the app is pretty transparent. While the rates can be higher than traditional loans, they are competitive for the payday loan market. The key here is the flexibility and the absence of those dreaded hidden fees.
Final Thoughts
If you're in need of quick cash and looking for an app that offers more than just a loan, Possible: Fast Cash & Credit might just be the app for you. Its user-friendly design, commitment to security, and credit-building features make it a standout choice in the crowded field of financial apps. Just remember, like any financial tool, it’s important to use it responsibly and ensure it fits your personal financial situation.
So, whether it's a car repair, medical bill, or just making ends meet until payday, give Possible a shot. It might be the financial helping hand you've been searching for.
4.4
28.60K Reviews
Pros
- Quick and easy loan approval process.
- User-friendly interface for easy navigation.
- Flexible repayment options available.
- No hidden fees or charges to surprise you.
- Secure data encryption ensures privacy.
Cons
- High interest rates compared to banks.
- Limited to certain regions or countries.
- Requires a stable internet connection.
- May affect credit score if not repaid.
- Customer support can be slow to respond.


